
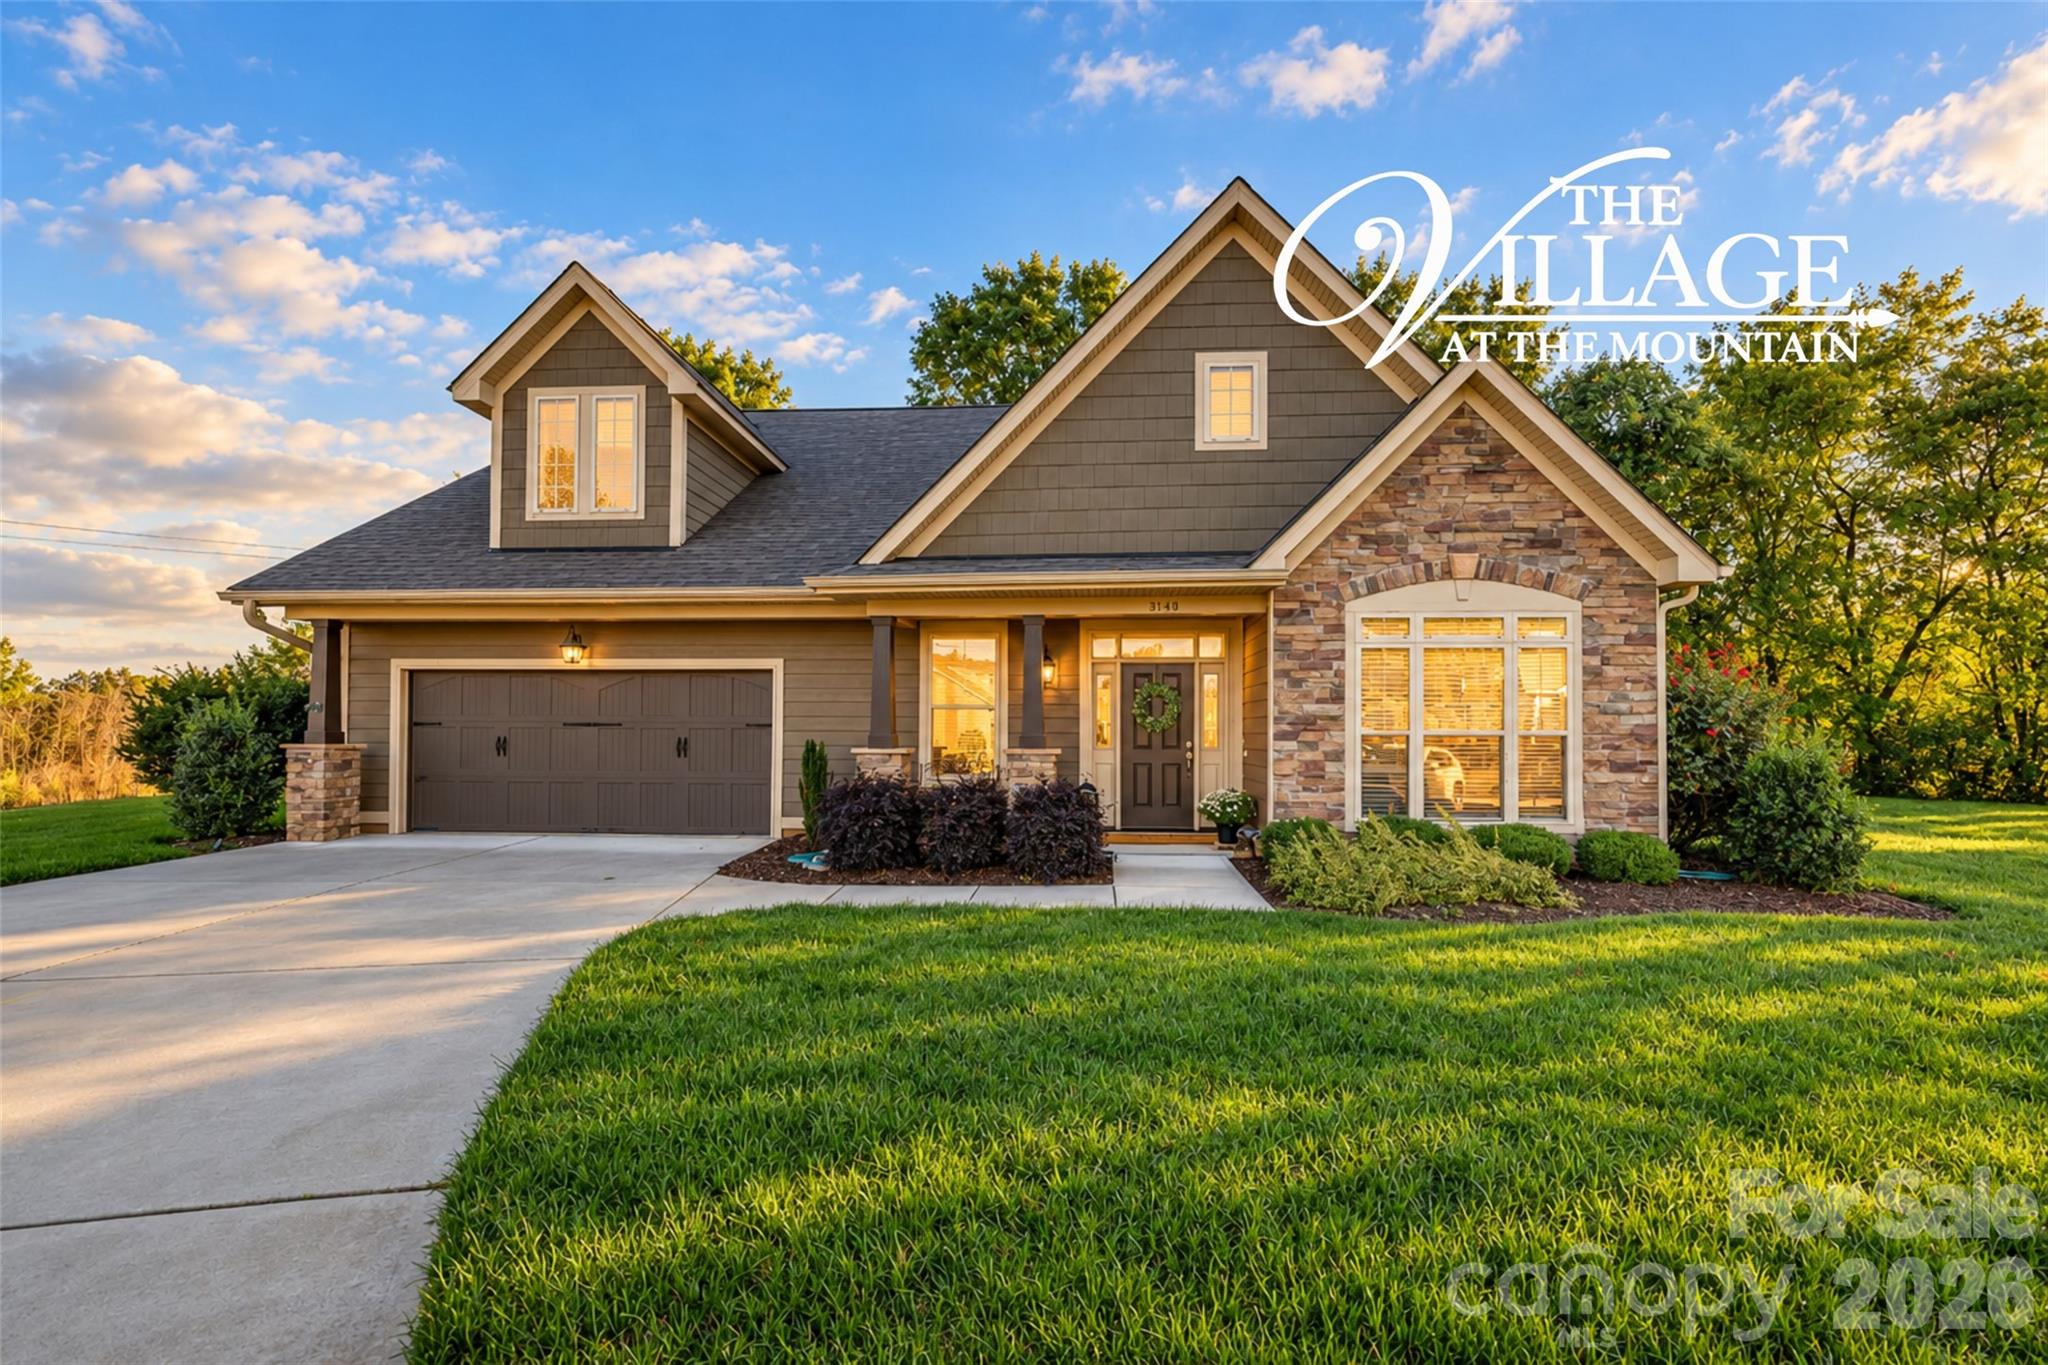

3141 Glacier Ct
1% of your loan amount, back at closing.
Finance this home with Oak Capital Mortgage and we credit you 1% of your loan amount, up to $7,500. Adjust the numbers to see your credit, then see what it can do for your payment.
Your snapshot
- No credit pull to see your numbers
- Works with conventional and FHA loans
- Once you apply, the credit stays with your loan through closing
Taxes & insurance
Three ways to use it
Same home, same credit. Pick the one that fits how long you plan to stay and what you want most: less cash at closing, a lower rate for good, or lower payments for the first few years.
Estimated totals add your property taxes and homeowners insurance (adjust them in the calculator) plus any mortgage insurance. HOA dues, if any, are extra. See the terms at the bottom of the page.
Text me my numbers for this home.
We’ll send this comparison to your phone and email, based on the price and down payment you picked. No credit pull, and no obligation.
- Your credit amount and all three options
- A quick call from your loan officer only if you ask for one
- A heads-up if the price changes
The listing agent, the listing agent, may be told you asked about this home.
By submitting, you ask Oak Capital Mortgage to send you these numbers and follow up about this home. See our Privacy Policy.
Get pre-approved for this home
A pre-approval from us shows the seller you’re serious and starts your application for the credit. Takes about 10 minutes.
Start my pre-approvalBook 15 minutes with Matthew Hassey
Walk through the options for your budget and timeline. No pressure, no credit pull.
Pick a timeIs this real money, or a catch?
It’s a real credit on your Closing Disclosure. It comes from how we price your loan, and your Loan Estimate shows exactly what you pay and what you’re credited, so you can compare it side by side with any other offer.
I already have a lender. Can they match this?
The credit is only available when Oak Capital Mortgage finances your purchase. You’re always free to choose any lender. If you’d like a second opinion, send us your Loan Estimate and we’ll show you the difference honestly.
What’s the difference between a permanent and a temporary buydown?
A permanent buydown lowers your rate for the life of the loan. A temporary buydown lowers your payment for the first one or two years, then it goes to the note rate. Temporary buydowns help most if you expect your income to rise or plan to refinance later.